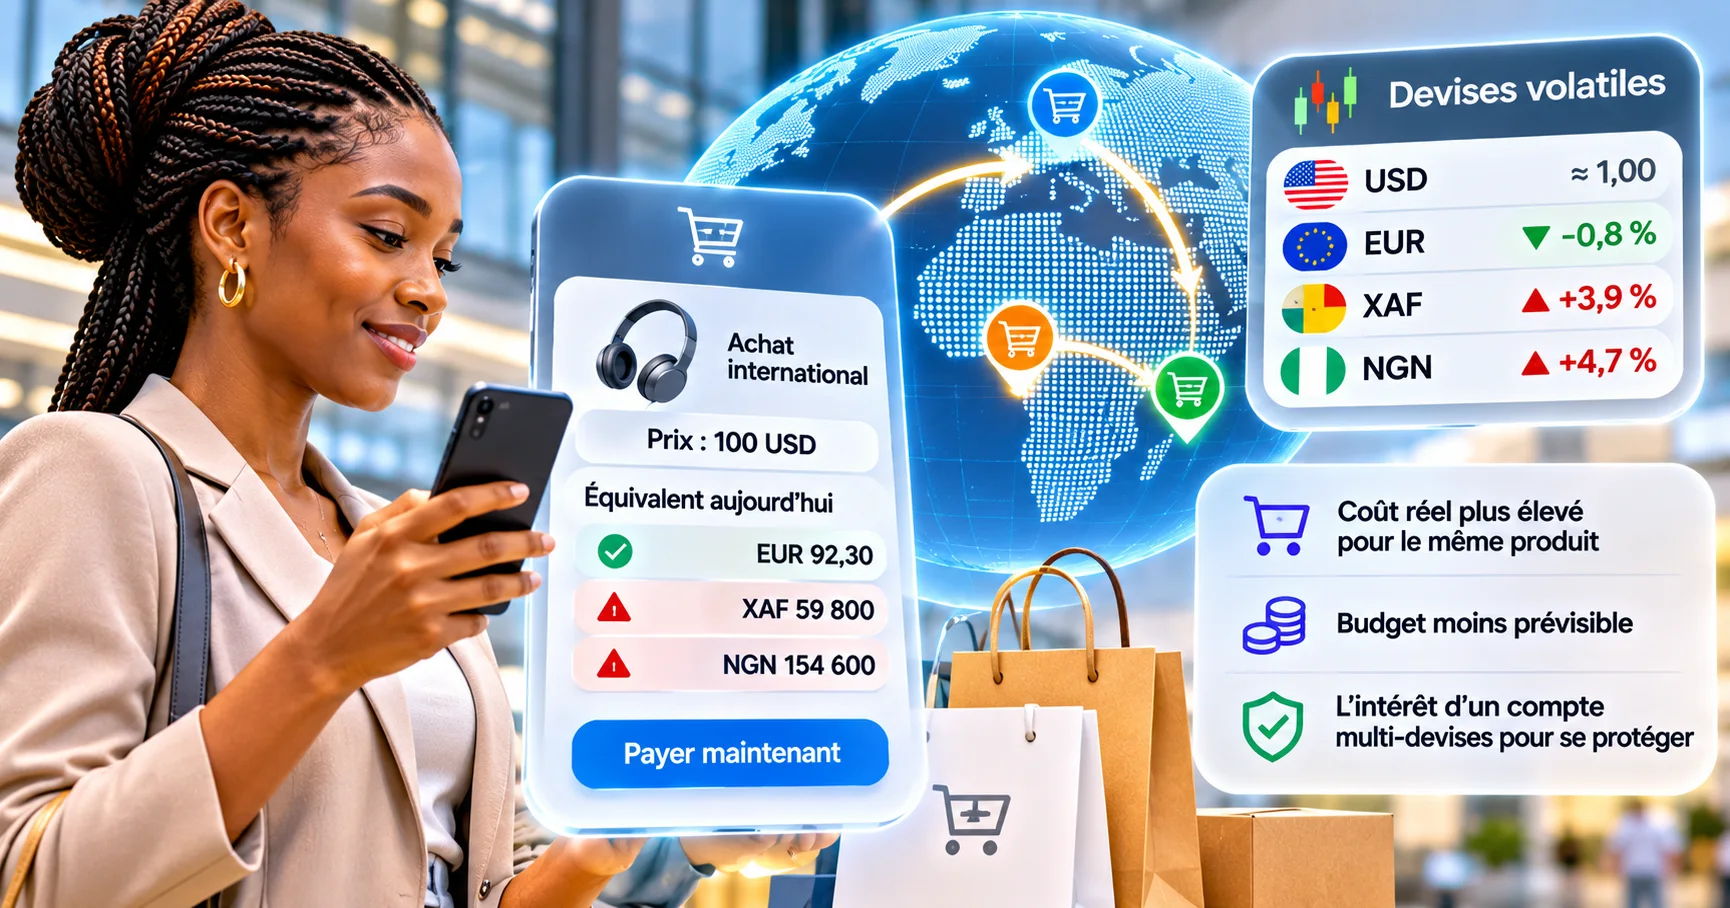
The Impact of Currency Volatility on Cross-border Purchasing Power
Bitcoin slid to $68,000 on 13 November, dragged down by turmoil in Nvidia shares and a rush of money into Anthropic's initial public offering. The move matters well beyond trading desks. For anyone who sends money home, invoices clients abroad or keeps savings in more than one currency, cross-border purchasing power just got harder to pin down — and the week's news explains why.
According to CoinDesk's market report, the drop reflects the fragility of digital assets when risk appetite turns. That fragility travels. A Filipino nurse in Dubai remitting part of her salary, a freelancer in Lagos billing a London client, a pensioner in Lisbon drawing an inheritance in dollars: all of them are, in effect, running small currency books, and none of them has a treasury department to hedge them.
International transfers, already exposed to fluctuating exchange fees, are becoming costlier and less predictable for expatriates and migrant workers. Bitcoin has dropped by 12% in just a few weeks, according to Decrypt's coverage of the 12-week low, deepening concern among crypto users who move value across borders.
The mechanism is simple and unforgiving. A sender locks in a quote, the platform executes hours later, and the rate has moved. On a $2,000 transfer, a 12% swing is $240 — roughly a week's rent in many emerging-market cities, and more than most remittance corridors charge in fees on the same amount. The fee is disclosed up front. The rate risk is not.
Currency volatility profoundly alters international savings strategies.
If you're receiving or sending funds in Bitcoin or other cryptocurrencies, the timing of the transfer can significantly affect the final value received. That cuts both ways, which is what makes it so hard to plan around.
Inflation's Effects on Multi-currency Savings
Inflation spares no one, but its effects on multi-currency accounts deserve particular attention. Savers who diversify to protect themselves can end up trapped by diverging inflation rates. The Bank for International Settlements has noted that inflation disparities can alter the real return on savings held in multi-currency accounts — a polite way of saying that a basket of currencies is only as stable as its weakest leg.
Consider a saver holding half their money in dollars and half in a currency losing 20% a year to inflation. Even if the nominal balance never moves, the real value of the second half falls by roughly a tenth of the total each year. The diversification looked prudent on paper. In practice it imported the weaker currency's problem into the whole portfolio.
When inflation spirals in one currency, purchasing power in another can be eroded through the exchange rate. That is a real challenge for anyone relying on the relative stability of certain currencies to preserve or grow wealth. The dollar, the euro and the yen do not move in lockstep, and the gaps between them are where savings quietly leak.
Risks for Transfer Platforms Amid Fluctuations
Money transfer platforms and fintech apps tracked by Belook's international transfer dossier have to adapt quickly to keep services secure and competitive. Fees are only part of it. Agility in the face of fast rate moves is what keeps customers from walking.
Sudden swings can trigger unexpected fee increases, making transfers more expensive at exactly the moment users can least afford it. Customers should watch the rate applied at execution, not the one advertised at checkout. A quoted rate is a promise with an expiry date, and on volatile days that expiry comes fast.
The operational side is just as exposed. Microsoft's 18-hour outage in South Africa showed how dependent payment and fintech services have become on a handful of cloud providers, and Crowdfund Insider's review of the year's technical disruptions makes the same point: when the infrastructure stumbles, transfers stall and rates move without you.
Fraud risk rises with the noise. The FBI has warned about an active $400 million crypto scam in which criminals replace a victim's face in videos to bait the next target, as CryptoSlate reported, and Crowdfund Insider detailed the North Korean FaceStealer operation behind it. A hurried transfer made under rate pressure is exactly the kind scammers count on.
What this means for you
- Plan your transfers: move money when rates suit you, and use tracking tools rather than guesswork.
- Diversify your savings: don't lean on a single currency or token; look at multi-currency options.
- Stay informed: follow macro and regulatory news that moves the currencies you hold.
Cross-border purchasing power is being tested on several fronts at once: a 12-week low in Bitcoin, inflation gaps between currencies, and platforms whose plumbing is only as reliable as their cloud provider. Adapting to fast moves is what protects a household budget now.
Prospects for Cryptocurrencies
Regulation and public perception keep shifting, and crypto is not immune to either. Decrypt's report on Fed Chair Warsh's questions about AI-driven inflation points to how monetary policy debate can feed straight into digital asset prices. If AI investment is pushing costs around in ways the Fed does not yet understand, rate expectations become harder to read, and crypto — the most rate-sensitive asset class retail investors own — absorbs the confusion first.
Institutional behaviour is worth watching too. JPMorgan's bitcoin and crypto-linked holdings are approaching $1 billion, Decrypt reported, a reminder that the same volatility retail users feel is now a line item on bank balance sheets. Meanwhile, long-dormant wallets moved $6.9 million after 16 years, according to Decrypt — a small sum, but a signal that old supply can surface without warning.
Market participants are split on what comes next. Joe Carlasare told Bitcoin Magazine he is a buyer amid "extreme fear", while Bill Miller IV made the supply case to the same outlet: "they're not printing more Bitcoin". Anthropic's chief executive, Dario Amodei, said he was "not super fussed" about market turmoil ahead of the company's listing. None of that settles the question a remittance sender actually faces: what will this money be worth when it lands?
Regulators may soon change the rules of the game. Trump's first Democratic picks for the SEC and CFTC could reshape crypto's supervisors, Decrypt noted, and clearer rules would affect how platforms price and settle cross-border flows. U.S. Bank, for its part, is adding 60 middle-market roles, Banking Dive reported — a sign that traditional lenders still see cross-border business as worth staffing.
For investors and crypto users alike, the lesson is to know the risks they are carrying. Resilience and agility are what keep a transfer, a savings pot or a payroll from being decided by the calendar rather than by choice.
Sources
- CoinDesk — Bitcoin plunges to $68,000 as Anthropic IPO frenzy adds to market jitters (13 November 2026)
- Decrypt — Bitcoin Hits 12-Week Low as Fed Rate Fears Undo Most of Summer Rally (13 November 2026)
- Decrypt — Fed Chair Warsh Wants Answers on AI Inflation—and Bitcoin May Feel the Impact (13 November 2026)