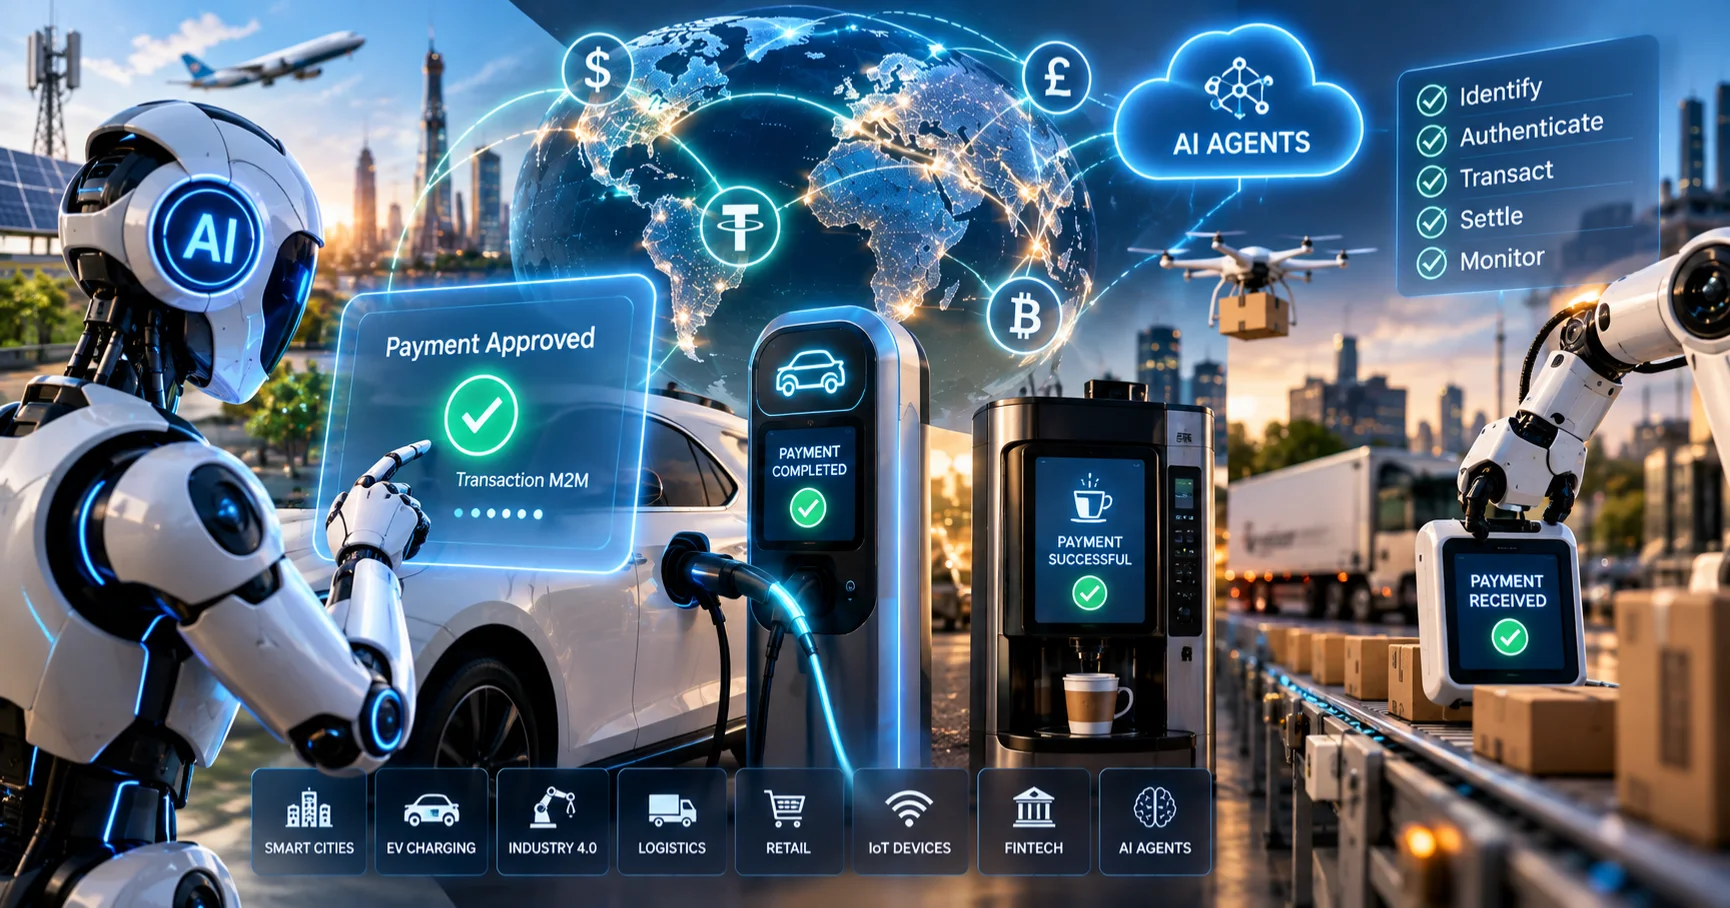
On September 25, Block joined the x402 Foundation, the effort to give AI agents a common way to pay online without a human in the loop, as PYMNTS reported. The same day, a dormant whale moved $380 million in bitcoin and nobody knows whether it sold, per CryptoSlate. Two stories with nothing in common except this: both describe money that increasingly moves between machines rather than people.
That's where the next fight over machine-to-machine payments is being decided. Not in the bitcoin price. In the plumbing.
Why machine-to-machine payments are leaving the lab
An AI agent buying a dataset, reserving a server or settling an API call has no card, no account and no handwritten signature. It needs a programmable rail, verifiable, settled in seconds. The x402 protocol does that: it turns a web request into a payment, with no form and no redirect. When Block, the company behind Cash App and Square, plugs into it, this stops being a research demo. It becomes infrastructure preparing to take volume.
The signal looks small. It isn't. The same week, Philippine fintech GCash filed for its IPO, which Warburg reads as proof that Southeast Asia can produce exits at scale, according to Crowdfund Insider. Consumer payment platforms have reached critical mass, and the next step is opening their pipes to customers who aren't people.
A single AI agent can fire thousands of micro-transactions an hour, where a human user generates a few dozen a month.The link nobody watches: conversion
Here's the second-order consequence most commentary misses. An agent paying in digital dollars doesn't care about foreign exchange. Its supplier lives in naira, rupees or zlotys and wants to be paid in local currency. Every micro-transaction therefore triggers a conversion, a compliance check and a settlement, often for tiny amounts.
On a $200 transfer, a $25 flat fee is absorbable. On a $0.40 payment, it is absurd. Legacy rails cannot process that volume per unit: they charge per file, not per millisecond. That's precisely the space stablecoins occupy, and the news confirms it. The Binance-Circle deal, analysed by CoinDesk, strengthens the USDC issuer against Tether. A digital currency distributed on the world's largest exchange is a settlement rail available everywhere, at any hour.
Granted, the counter-argument holds. Stablecoins still rest on centralised reserves, watched by regulators who move fast. Hester Peirce's announced departure from the SEC next week is a reminder that American regulatory clarity still depends on a handful of people rather than a settled framework, as CoinDesk notes. Building a corporate treasury on that base calls for caution, not faith.
The next big customer for cross-border payments will be neither a person nor a company: it will be software that buys, pays and gets refunded without ever filling in a form.
What businesses moving money should prepare now
Three workstreams, in this order.
- Map the flows that will automate. API billing, software licences, market data, programmatic advertising: these are the first line items an agent will pay on your behalf. If getting paid requires a manual wire and an email confirmation, you'll lose those clients.
- Separate the settlement rail from the conversion rail. Settling in digital currency doesn't remove the need to convert for the beneficiary. The question for your provider isn't "do you accept stablecoins?" but "what does it cost to convert $0.40, and how long does it take?"
- Treat compliance as a product. An agent paying a thousand times an hour must be identifiable, capped and traceable. Manual checks no longer scale.
For a marketplace or a services platform, the logic is the same: collecting a programmable payment means being able to hold it, release it and refund it without friction. That's what an escrow mechanism built on a multi-currency account does, rather than a classic international wire. Our file on cross-border transfers walks through those structures.
The risk everyone underrates
Money that moves without a human obviously attracts those who need no permission. The Bitget breach, roughly $388 million attributed to North Korea-linked groups according to Bitcoin Magazine, shows how fast a compromised key drains a liquidity pool. An agent holding a balance and signing automatically is a softer target than a treasurer approving by hand.
The answer isn't to refuse automation. It's to cap mandates, ring-fence balances and verify every counterparty at settlement, not once a year.
What this means for you
- If you sell digital services: start testing a programmable payment link now. An automated buyer will never fill in a SWIFT transfer form.
- If you send money abroad: compare the all-in cost, flat fees included. On small amounts, the fixed fee decides everything, not the headline exchange rate.
- If you run a multi-currency treasury: set per-counterparty and daily caps before you authorise any automatic payment.
One thing to watch: the first stable specification of the x402 protocol from its founding members. That document will tell us whether machine-to-machine payments stay a technical demo or become, from 2027, a line item in the accounts of every business invoicing across borders.
Sources
- PYMNTS — Block Joins x402 Foundation to Drive Agentic Commerce Standards (25 September 2026)
- CryptoSlate — Dormant whale moves $380M Bitcoin, leaving the sale question unanswered (25 September 2026)
- Crowdfund Insider — Fintech GCash’s IPO May Show Southeast Asia Can Deliver Scale Exits: Warburg (26 September 2026)
- CoinDesk — Binance deal gives Circle a boost in stablecoin race with Tether, analysts say (26 September 2026)
- CoinDesk — U.S. SEC's steadiest crypto advocate, Hester Peirce, to depart next week (25 September 2026)
- Bitcoin Magazine — North Korean Hackers Linked to $388M Bitget Crypto Exchange Theft: CEO (25 September 2026)